

Wallet - Digital Card Wallet
by Wallet Assistant
4.7
- Safety
- 100% Safe
- Category
- Tools
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
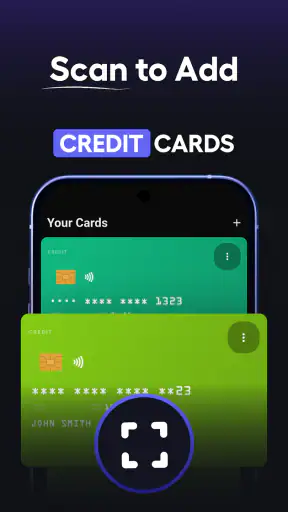
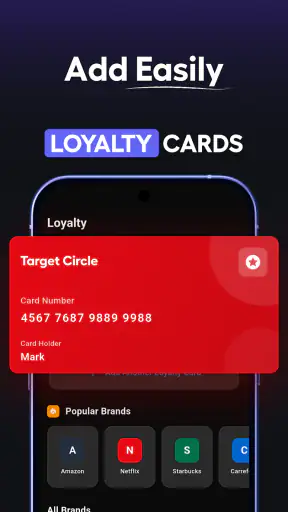
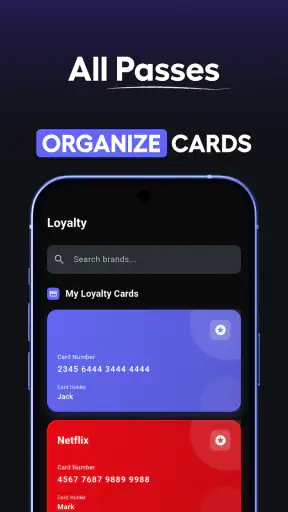
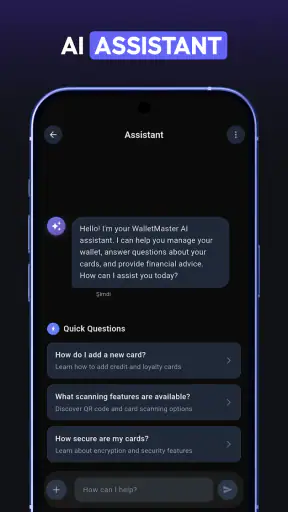
 Analysis by Getfullapps
I started using Wallet - Digital Card Wallet for a simple reason: my physical wallet had become a small collection of cards I rarely carried at the same time. Loyalty cards, membership barcodes, and payment cards were spread between different places, and finding the right one at a checkout was often more awkward than it should have been. This free tools app from Wallet Assistant brings those items together in one mobile space, and its usefulness becomes especially clear in a household where people regularly coordinate errands.
My overall impression is positive, but it is not a complete replacement for every physical card or every banking application. It works best as a focused organizer for cards and barcodes. The main benefit is not flashy automation; it is reducing the number of places I need to check before leaving home. With a 4.7 average from around 23 thousand ratings and more than a million installs, it has clearly found an audience among people who want a straightforward digital wallet rather than a full financial-management service.
How the wallet fits into everyday household routines
I find the household side of a card wallet works best when it supports clear routines rather than trying to make everyone’s cards interchangeable. Decide which loyalty barcodes are useful to share, keep personal payment details on each person’s own phone, and agree on simple card names so a quick errand does not turn into a search. That approach also makes it easier to judge whether the app’s free access delivers enough value for your household.
One phone, several practical errands
A realistic household example is a weekend shopping trip. One person may be carrying the payment card, while another remembers the supermarket loyalty card, pharmacy membership, or a barcode needed for a pickup. Instead of passing around a bulky physical wallet, the person holding the relevant phone can open the saved card and present its barcode. That small change makes the app useful for coordination, even when everyone is not using the same device.
I found the distinction between “organizing cards” and “sharing financial access” important. The app can place credit cards, loyalty cards, and barcodes in one location, but that does not mean every household member should use the same phone or have access to every card. A barcode for a store account is one thing; a payment card contains much more sensitive information. I would treat the app as a personal wallet first and a household convenience second.
For shared errands, the smoothest routine is to decide in advance who will present which card. If one person handles payment, that person should keep payment details on their own device. Another household member can keep loyalty cards or collection barcodes separately. This avoids turning a convenient organizer into a shared vault with unclear boundaries.
What it is good at, and what it is not trying to be
The app belongs in the tools category, and that description matches my experience. It is designed to help me retrieve card information quickly, not to replace a bank’s secure banking environment, manage a family budget, or coordinate household spending. The store summary describes a digital wallet for credit cards, barcodes, and loyalty cards, and I think that narrow purpose is its strength.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Compared with carrying every plastic card, the phone-based approach is lighter and easier to search mentally. Compared with keeping screenshots in a photo gallery, a dedicated wallet gives the cards a more intentional home. A gallery can become cluttered with unrelated images, while a wallet is built around the task of opening a card at the right moment. Compared with a bank app, however, this is a different tool: I would use a bank app for account activity and transactions, and this wallet for organizing card representations and barcodes.
That separation matters. Someone looking for contactless payment, transaction history, spending alerts, or account management may be better served by the official app from their bank or payment provider. Someone who mainly wants to stop carrying loyalty cards may find this app more convenient than a collection of unrelated retailer apps.
Setting it up without blurring account boundaries
My advice is to begin with a small, deliberate collection rather than adding every card immediately. Start with the cards used weekly: the supermarket loyalty card, a frequently visited retailer card, a gym or membership barcode, and any other item that regularly causes wallet clutter. This makes it easier to learn the app’s presentation flow and notice whether the barcode is easy to find under real checkout pressure.
For a household, setup should happen separately on each person’s phone. I would not create a shared arrangement simply because several people visit the same stores. A shared device can be practical in a family car or at a common counter, but it creates an obvious privacy issue when payment cards are involved. Keeping personal payment cards on personal devices is the safer boundary, while non-sensitive loyalty cards can be coordinated by agreement.
There is also a useful distinction between a card being “available” and a card being “appropriate to share.” A household may share a loyalty account, but the card can still reveal an account number or membership identity. Before handing a phone to a child, guest, or temporary helper, I would open only the specific barcode needed and avoid leaving the wallet on a general card list.
The app is free to install, while in-app purchases range from around ten dollars to around seventy dollars per item. That makes it sensible to explore the basic workflow before spending anything. I would not pay simply because the app has many cards to organize; I would first decide whether its handling, visibility, and retrieval speed fit my routine.
Making retrieval reliable at the checkout
The most valuable habit is organizing cards by how I use them, not by how important they sound. A card used every day deserves to be easy to reach. A rarely used membership card can sit farther down the list. This sounds obvious, but it prevents the common mistake of arranging everything alphabetically and then scrolling through a long collection while a queue forms behind me.
I also recommend testing each barcode before relying on it. A barcode that looks clear on a phone may still be awkward for a scanner if the screen is dim, the phone is held at a poor angle, or a protective screen makes viewing difficult. The practical test is simple: open the card before reaching the register, raise the screen brightness if needed, and hold the display steady. That workflow is more dependable than waiting until the cashier asks for the card.
For shared household use, a second useful habit is naming cards consistently. If two people have similar retailer cards, unclear labels can lead to the wrong one being displayed. A short personal marker or a clear store name can reduce hesitation. I would avoid adding private notes that expose more information than necessary, especially if someone else may occasionally handle the phone.
Another trade-off is convenience versus concentration. Keeping everything in one wallet reduces app switching, but it also creates one place containing many types of card information. I prefer the convenience for loyalty cards and barcodes, while remaining more cautious with credit cards. The more sensitive the card, the more important it is to consider who can unlock the phone and who may see the screen during an ordinary errand.
Coordinating without assuming family controls
Household coordination works best through routines rather than assumptions about built-in family management. I would not expect the app to decide which person should see which card or to separate adult and child accounts automatically. The practical solution is to agree on responsibilities: one person maintains their payment cards, another keeps shared loyalty cards, and everyone knows where the commonly used barcode is stored.
This arrangement is particularly useful for couples who shop together but do not want to merge all financial information. A shared supermarket card can be available to both people, while personal credit cards remain separate. It preserves convenience without treating the household as one undifferentiated account.
For a parent helping a child with errands, I would use the app selectively. A child might need a library, club, transport, or store barcode, but that does not mean the child should receive access to an adult’s complete wallet. Showing one card at a time is a better practice than handing over an unlocked phone and asking the child to search.
Older relatives may also appreciate the reduction in physical cards, but the experience depends on comfort with phone screens and unlocking. In that situation, the best introduction is not to transfer everything at once. Add one or two frequently used cards, practice opening them at home, and keep a physical backup until the digital routine feels natural.
Age, trust, and the meaning of “Everyone”
The content rating is Everyone, which makes the app broadly suitable from a content perspective. That should not be confused with unrestricted access to financial information. Age suitability and privacy suitability are different questions. A young person may be able to use a barcode wallet safely, while still not being the right person to handle payment cards belonging to another household member.
Trust is therefore more important than the rating alone. I would consider who can unlock the device, whether notifications or previews might expose information, and whether the phone is regularly shared. These are household decisions rather than features I would assume the app makes for me.
The same principle applies to guests. If a friend is borrowing a phone to scan a loyalty card, I would open the exact card first instead of asking them to navigate through the full collection. It takes a few extra seconds, but it limits accidental exposure and makes the interaction less confusing.
People who need formal separation between work cards, personal cards, and family cards may find a dedicated wallet insufficient on its own. In that case, separate devices, separate user profiles where available on the operating system, or official provider apps may offer clearer boundaries. The app can still be useful within one of those spaces, but it should not be treated as a substitute for device-level privacy controls.
Performance expectations and everyday friction
The current version is 6.2.5, and the minimum operating system is Android 7.0. That makes the app accessible to many older Android phones, which is helpful for households that do not upgrade devices frequently. Still, compatibility is not the same as comfort. A phone with a small display, a weak battery, or a slow unlock process can make any digital wallet feel less convenient than a physical card.
The main friction I notice with this kind of app is situational rather than complicated. A dead battery, a locked phone, poor screen visibility, or a barcode that is difficult to present can turn a simple checkout into a delay. I would keep essential identification and a backup payment method available in physical form. The app reduces wallet bulk; it does not eliminate the need for contingency planning.
There is also a mental cost to adding too many cards. A digital collection can grow faster than a physical wallet because storage feels unlimited. If I save every temporary barcode, expired membership, and rarely used card, the app becomes another cluttered drawer. A monthly cleanup is worthwhile: remove cards that no longer matter, rename confusing entries, and keep the first screen focused on current routines.
That cleanup is especially important on a shared household device. When several people add items without a clear naming convention, the wallet can become difficult to navigate. A short list with obvious labels is more useful than a complete archive. I would rather keep an occasional card elsewhere than make the everyday cards hard to reach.
Who should choose it, and who should skip it
I think this app is a good fit for someone who carries many loyalty cards, frequently uses barcodes, and wants one dedicated place for them. It is also suitable for a household that wants to coordinate store memberships without merging all personal payment information. People moving away from screenshots or scattered retailer apps may notice the biggest improvement because the app gives those cards a single purpose-built home.
I would be more hesitant to recommend it as the main solution for someone who expects a complete financial wallet. If your priority is bank transfers, transaction monitoring, contactless payment management, expense categorization, or formal family permissions, an official banking or payment app is likely the better choice. This app’s value comes from organization, not from replacing those services.
I would also skip it if you carry only one or two cards and already have a reliable alternative built into your phone. Adding another app may not improve your routine. The best reason to use it is repeated friction: searching for cards, carrying too much plastic, or switching among several retailer apps. Without that problem, the benefit may be modest.
Privacy-conscious users should make a personal decision about whether storing card representations on a phone is acceptable. I would use it more freely for loyalty cards and barcodes than for sensitive payment information, and I would pay close attention to who can access the device. The app can simplify organization, but responsible handling still depends on the user.
My household verdict
After using it as a practical card organizer, I see Wallet - Digital Card Wallet as a focused and useful tool rather than an all-purpose financial platform. Its strongest quality is the way it turns a messy collection of loyalty cards and barcodes into something I can reach during an ordinary errand. The free entry point makes it easy to try, and the broad Everyone rating and Android 7.0 requirement make it approachable for many users and older household phones.
My recommendation is to start small, keep personal payment cards separate from shared loyalty cards, and test the barcode presentation before depending on it in a busy store. Those habits address the most realistic weaknesses: clutter, unclear account boundaries, and overconfidence in a phone as the only backup. Used with those limits in mind, it can make shopping and membership check-ins noticeably less cumbersome.
For me, the deciding question is simple: do you regularly wish your cards were easier to find? If the answer is yes, this app earns a place on the phone. If what you really need is banking, payments, or strict household access management, I would choose a more specialized alternative. For everyday card organization, though, Wallet Assistant has built a practical solution that is most convincing when used deliberately rather than as a container for everything.
Pros
- Keeps loyalty cards organized and easy to access.
- Reduces the need to carry physical cards in your wallet.
- Quickly displays card barcodes at participating stores.
- Simple interface that is easy for first-time users.
- Can help reduce paper and plastic card clutter.
Cons
- Not every store’s barcode scanner may read the digital card correctly.
- Adding cards manually can be time-consuming.
- Some features may depend on device camera permissions.
- Limited usefulness if your favorite stores are unsupported.
- A lost or unprotected phone can expose stored card details.
FAQs for Wallet - Digital Card Wallet
What is Wallet - Digital Card Wallet, and what can I use it for?
Wallet - Digital Card Wallet is designed to keep digital versions of your loyalty cards, membership cards, coupons, tickets, and other scannable passes in one place. Instead of carrying a physical wallet full of plastic cards, you can open the app when shopping or attending an event and display the relevant barcode or QR code. Its usefulness depends on which card formats and merchants are supported.
Is Wallet - Digital Card Wallet safe for storing my cards and personal information?
Before adding cards, review the app’s privacy policy and requested permissions carefully. A digital wallet may store card numbers, barcodes, names, or other identifying details on your device or through a connected backup service. Avoid adding sensitive payment information unless the app clearly supports secure payment features. Using a device lock, biometric protection, and current software can provide additional protection.
Can I use Wallet - Digital Card Wallet for bank cards and contactless payments?
The app is primarily intended for digital passes such as loyalty cards, coupons, tickets, and membership cards, rather than automatically replacing a dedicated payment service. Whether a bank card can be added or used for contactless payments depends on the app’s features, your device, your country, and participating financial institutions. Check the current listing before relying on it for everyday payments.
Will my digital cards work without an internet connection?
Many stored barcodes and QR codes can usually be displayed offline once the card has been added successfully, which is helpful in shops, airports, or venues with poor connectivity. However, downloading new passes, synchronizing data, updating tickets, or validating certain time-sensitive credentials may require internet access. It is wise to open important cards in advance and keep the app updated.
How do I add, organize, or remove cards in Wallet - Digital Card Wallet?
Cards are generally added by scanning a barcode, entering card details manually, importing a supported pass, or selecting a compatible template. After adding them, you can organize cards so frequently used ones are easier to find at checkout. When a card expires or is no longer needed, remove it from the app and check whether any backups or synchronized copies must also be deleted.

Wallet - Digital Card Wallet
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via contact@yildizco.net, visit https://www.yildizco.net, or review their https://www.yildizco.net/wallet.










